Chandra Wibowo
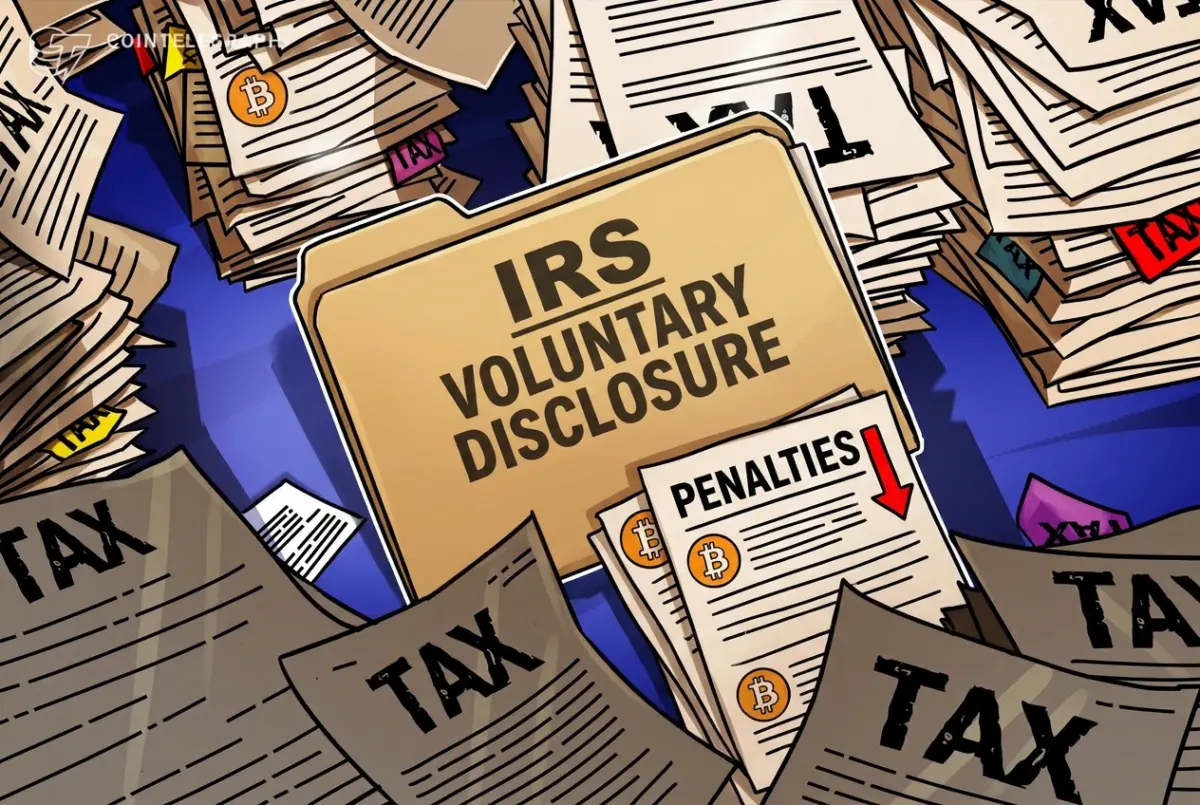
The U.S. Internal Revenue Service (IRS) is poised to significantly reform its voluntary disclosure program, aiming to expedite the resolution of past tax violations and offer taxpayers more adaptable payment arrangements. This strategic overhaul, expected to be implemented before the end of 2026, signals a notable shift in the agency’s approach to encouraging compliance and addressing historical non-disclosure, particularly as the complexities of digital asset taxation continue to evolve. The proposed changes are designed to incentivize more individuals and entities to proactively come forward with their tax discrepancies, thereby reducing the burden on both taxpayers and the IRS.
Key Programmatic Changes and Objectives
At the heart of the impending overhaul lies a commitment to significantly reducing the time it takes to resolve cases. IRS Criminal Investigation Chief Jarod Koopman disclosed that the agency is targeting a resolution timeframe of approximately 120 days from the moment a taxpayer completes the necessary submission process. This aggressive timeline represents a substantial departure from the current program, which, according to reports, can extend to a year or even longer. The accelerated pace is intended to provide greater certainty and relief to individuals who have been living with the anxiety of potential tax evasion charges.
Furthermore, the IRS is exploring more flexible payment options for those coming forward. The agency is reportedly considering allowing taxpayers to settle their outstanding tax liabilities through installment plans or offers in compromise. These options could prove invaluable for individuals facing significant back taxes, providing a more manageable path to compliance than a lump-sum payment. This flexibility is a critical component in making the voluntary disclosure program more accessible and less financially daunting for a wider range of taxpayers.
Handling of Digital Assets Within the Revised Framework
A crucial aspect of the program revision is its approach to digital assets, a rapidly expanding and often complex area of tax non-compliance. Contrary to speculation about a separate, specialized disclosure process for cryptocurrencies and other digital assets, Chief Koopman clarified that these will be handled through the same voluntary disclosure procedures as other forms of tax non-compliance. This integrated approach suggests that the IRS views digital asset tax issues as fundamentally similar to traditional tax evasion or underreporting, albeit with unique technical challenges.
This decision to not create a separate track for digital assets indicates the IRS’s confidence in its existing frameworks to accommodate these new forms of wealth and income. However, it also places a greater emphasis on taxpayers understanding how their digital asset activities translate into taxable events under existing tax law. The IRS will likely rely on its enforcement and compliance divisions to develop the necessary expertise and guidance to effectively process these disclosures.
Reduced Penalties and the Nature of Voluntary Disclosure
One of the most significant incentives for taxpayers to participate in the revised program is the anticipated reduction in penalties. While specific figures have not yet been released, Koopman indicated that penalties under the overhauled program would be "substantially lower" than those currently imposed. This is a strategic move by the IRS to balance the need for enforcement with the goal of encouraging voluntary disclosure. The current voluntary disclosure program is primarily designed for individuals whose willful failure to comply with tax laws could expose them to criminal prosecution. The implication of lower penalties suggests the IRS may be broadening the program’s appeal or offering a more lenient outcome for those who self-report, even if their non-compliance was willful.
It is important to distinguish this program from the IRS’s standard procedures for correcting unintentional reporting errors. The existing voluntary disclosure program is not intended for taxpayers who made simple mistakes or omissions due to oversight. Instead, it targets individuals who intentionally avoided their tax obligations. The revised program, while still focused on willful noncompliance, appears to be recalibrating the punitive response to encourage more proactive engagement with the tax system.
Background and Context of the Voluntary Disclosure Program
The IRS’s voluntary disclosure program has historically served as a critical tool for the agency to uncover unreported income and assets. For decades, individuals facing potential criminal tax charges have been able to mitigate their risks by voluntarily coming forward, admitting their non-compliance, and cooperating with the IRS. The program’s success has often hinged on the understanding that a voluntary disclosure can significantly reduce the likelihood of criminal prosecution and potentially lower penalties compared to being discovered through an IRS investigation.
The program evolved significantly following major international efforts to combat offshore tax evasion. In the early 2010s, after the UBS tax evasion scandal, the IRS offered a streamlined Offshore Voluntary Disclosure Program (OVDP) that led to billions of dollars in back taxes, interest, and penalties being collected. While the OVDP has since concluded, the principles of voluntary disclosure continue to be a cornerstone of tax enforcement.
The current landscape, however, is marked by increasing complexity. The rise of digital assets, globalized financial markets, and new forms of income generation present ongoing challenges for tax authorities. The IRS has been actively seeking ways to adapt its enforcement strategies to these evolving realities. The planned overhaul of the voluntary disclosure program is a direct response to these challenges, aiming to make the process more efficient and attractive in a modern economic environment.
Legislative Developments and Potential Synergies
Adding another layer to the evolving landscape of tax compliance, lawmakers are concurrently considering separate legislative initiatives specifically aimed at crypto taxpayers. A proposed bill, which has advanced through the House Ways and Means Committee, includes provisions for a voluntary disclosure program tailored for cryptocurrency users. This proposed program, detailed in Section 502 of the Digital Asset Tax Certainty Act, would offer a structured pathway for correcting past reporting errors, including those stemming from unintentional mistakes.
This legislative effort is distinct from the IRS’s planned program overhaul. While the IRS program focuses on addressing willful tax noncompliance, the proposed Digital Asset Tax Certainty Act appears to be designed to provide a remedy for a broader range of errors, including those made in good faith. The existence of such a bill highlights the growing recognition among policymakers of the unique challenges and opportunities presented by digital assets in the tax realm. The interplay between the IRS’s administrative program changes and potential legislative reforms could create a multifaceted environment for taxpayers to address their past tax obligations.
Analysis of Implications and Future Outlook
The IRS’s move to revamp its voluntary disclosure program carries several significant implications. Firstly, it signals a proactive stance by the agency to encourage compliance in an era of increasing financial complexity. By offering faster resolutions and more flexible payment options, the IRS is attempting to lower the barriers to entry for individuals and businesses who may have fallen out of compliance. This could lead to a substantial increase in voluntary disclosures, bringing more previously unreported income and assets into the tax base.
Secondly, the emphasis on resolving cases within 120 days suggests a significant investment in the IRS’s operational capacity and technological infrastructure. The ability to process disclosures and conduct investigations at such a pace will require streamlined workflows, efficient data analysis, and well-trained personnel. If successful, this could set a new standard for tax agency efficiency.
Thirdly, the handling of digital assets through existing procedures, rather than a separate track, underscores the IRS’s ongoing effort to integrate the taxation of these assets into the broader tax system. While this may simplify the administrative process for the IRS, it places a greater onus on taxpayers to understand their tax obligations related to digital assets and to seek professional advice if needed.
The timing of the overhaul, slated for implementation before December 2026, suggests that the IRS is working diligently to align its administrative practices with the evolving needs of taxpayers and the broader economic landscape. The success of this initiative will likely depend on clear communication from the IRS regarding the specifics of the program, including penalty structures and eligibility criteria. Furthermore, the public’s perception of the program’s fairness and effectiveness will be crucial in determining its overall impact.
As the IRS embarks on this significant reform, taxpayers who have outstanding tax violations, particularly those involving digital assets, should closely monitor the program’s rollout. The prospect of lower penalties and faster resolutions offers a compelling incentive to come forward and rectify past non-compliance, thereby avoiding potentially more severe consequences down the line. The agency’s commitment to modernization and flexibility in its voluntary disclosure program marks a notable development in U.S. tax administration, reflecting a strategic effort to adapt to the challenges and opportunities of the 21st-century economy.