 Metty Iskandar
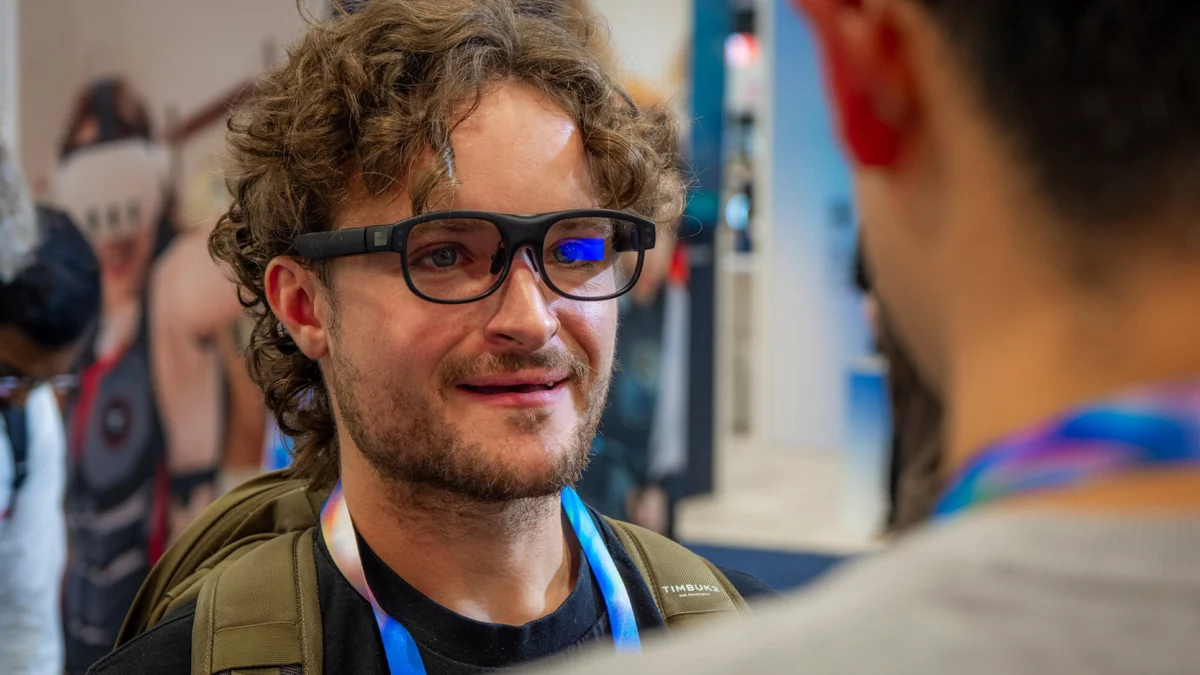
The smart glasses sector is experiencing an unprecedented surge in adoption, with global shipments of AI-enabled eyewear soaring by a remarkable 263% year-over-year in the first half of 2026. This dramatic increase, detailed in Counterpoint Research’s latest Intelligent Eyewear Market Tracker, signals a significant shift in consumer interest and technological maturation within what was once considered a niche market. The driving force behind this expansion is largely attributed to the more accessible and affordable display-less AI glasses, which have captured the lion’s share of the market.
Display-Less AI Glasses Lead the Charge
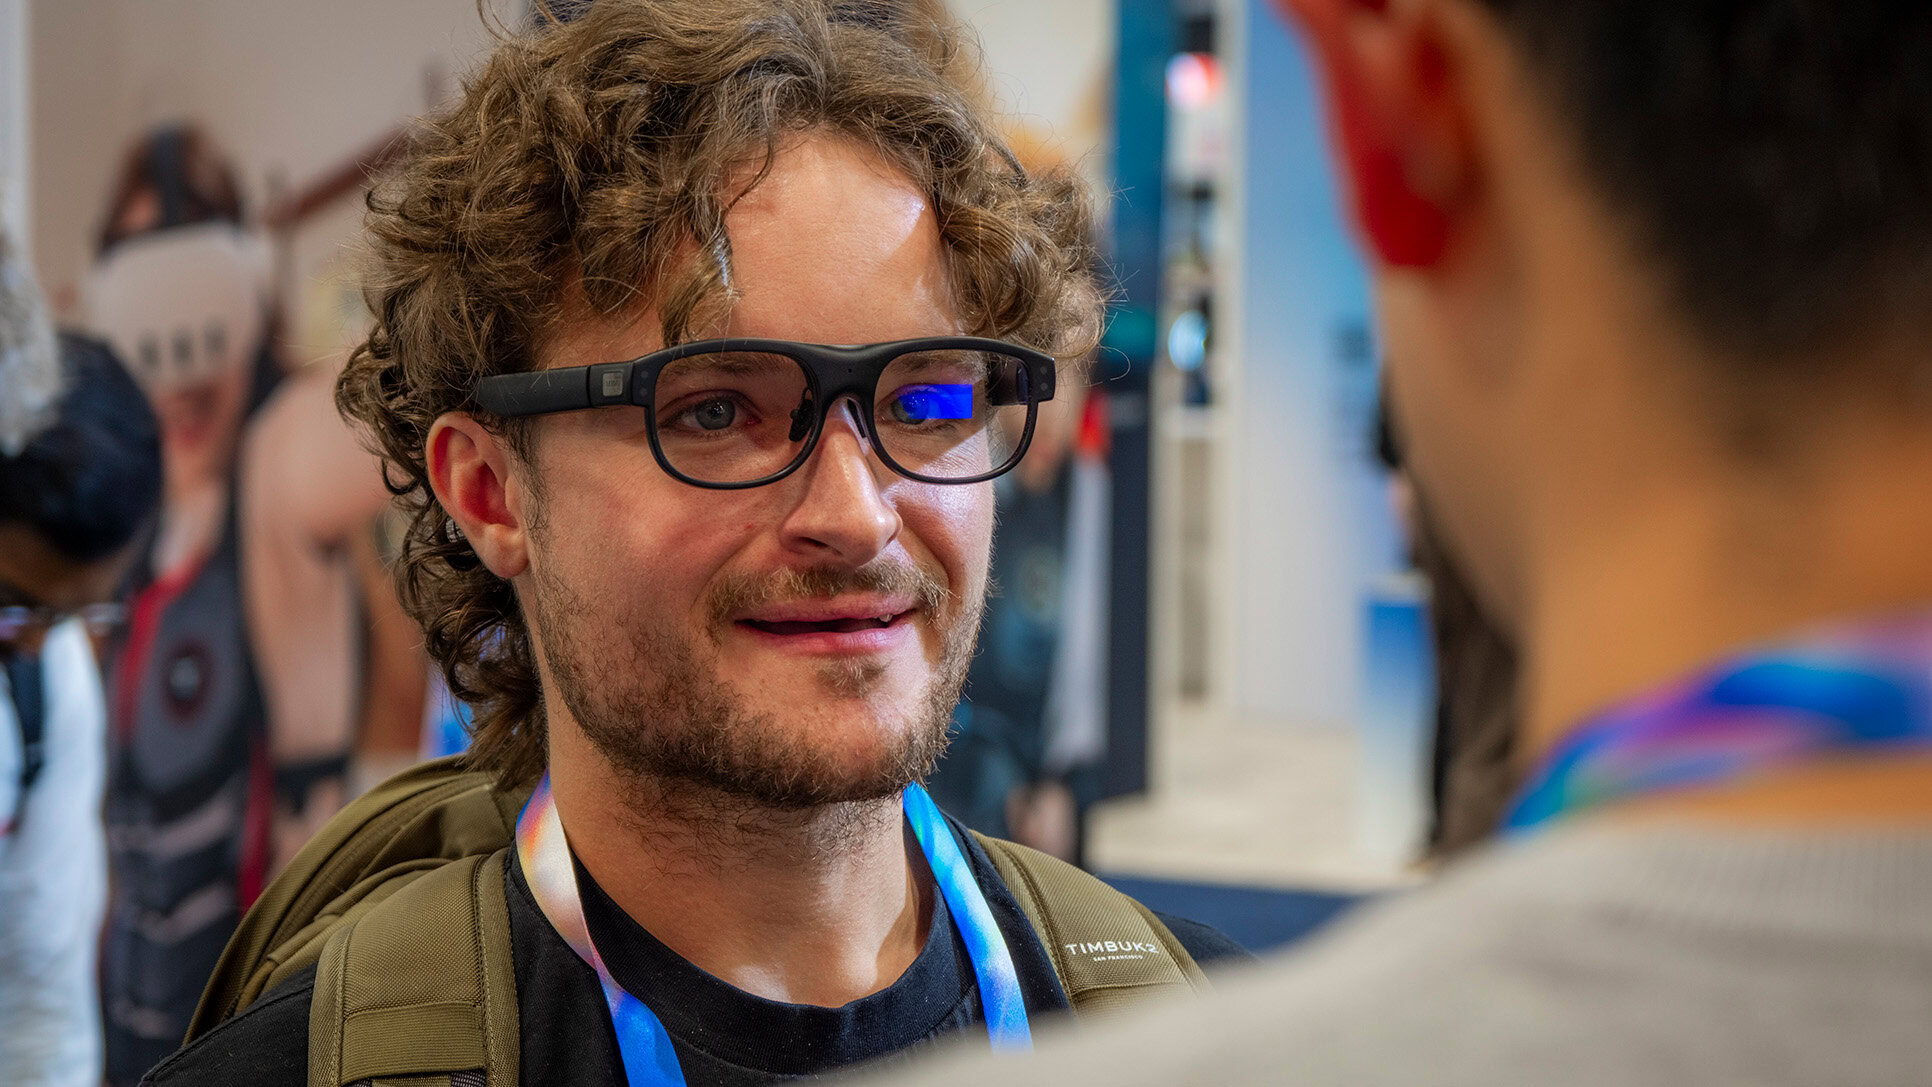
Shipments of display-less AI glasses, encompassing devices like the popular Ray-Ban Meta AI Glasses, saw an impressive year-over-year increase of 258%. This segment also demonstrated robust sequential growth, rising by 22% compared to the latter half of 2025. This category of smart glasses prioritizes audio capabilities, camera functionality, and AI-powered assistance without the visual overlay of augmented reality, making them a more practical and less intrusive option for everyday use.
Meta, a dominant player in the technology landscape, has established a formidable presence in this display-less segment. The company commands a staggering 94% of all display-less AI glasses shipments during the first half of 2026. Meta’s own shipments within this category experienced a substantial 260% year-over-year growth. This impressive performance can be attributed to several strategic initiatives, including the introduction of new Ray-Ban variants, aggressive expansion into international markets, targeted retail promotions, and the launch of more budget-friendly Meta-branded smart glasses. These efforts have clearly resonated with consumers seeking integrated AI functionalities within familiar wearable form factors.
Augmented Reality Glasses Show Even Faster Growth
While currently representing a smaller fraction of the overall market, smart glasses equipped with augmented reality (AR) displays are exhibiting even more rapid growth rates. Shipments of AR and AI glasses combined surged by an extraordinary 449% year-over-year. This steep climb, while originating from a smaller base, underscores the burgeoning interest in immersive digital experiences delivered directly through eyewear.
In this nascent AR segment, Rokid emerged as a leader, securing a 41% market share. Meta followed closely with 37% of shipments. The strong performance of AR glasses in China, which accounted for 45% of global shipments, is partly attributed to the region’s more established component supply chain. This suggests that advancements in manufacturing and component availability are crucial factors enabling the rapid development and deployment of sophisticated AR eyewear.
Market Growth Amidst Emerging Challenges
The rapid expansion of the smart glasses market is not without its potential obstacles. Counterpoint Research has identified two significant near-term headwinds: rising component costs and increasing public concern regarding cameras and data privacy.
The escalating cost of components has been a persistent issue across various technology sectors, and smart glasses are no exception. As demand increases and manufacturers strive to incorporate more advanced features, the cost of essential components like micro-displays, processors, and sensors can impact both production costs and final retail prices.
More pressingly, public apprehension surrounding the ubiquitous presence of cameras in smart glasses is a growing concern. As these devices move from early adopters to the mainstream, the implications for privacy become more pronounced. Meta’s recent challenges with the recording indicator on its smart glasses serve as a pertinent example. Reports highlighted a loophole that allowed users to obscure the LED indicator after recording had already commenced, raising questions about transparency and user awareness. Such incidents, even if resolved, can erode consumer trust and necessitate stricter regulatory oversight.
Future Outlook and Potential Innovations
Despite these challenges, Counterpoint Research remains optimistic about the long-term growth trajectory of the AI glasses market. The firm anticipates that these headwinds will not derail the overall expansion, but rather will spur innovation in product design and functionality.
A significant area of expected innovation lies in the development of form factors that circumvent or mitigate privacy concerns associated with cameras. This includes a potential surge in camera-free AI audio glasses. Reports from the previous week suggest that Meta is actively exploring such a product, potentially focusing on microphone and AI capabilities rather than visual recording. This strategic pivot would cater to a segment of consumers who are drawn to the AI assistance and connectivity offered by smart glasses but are hesitant due to privacy implications.
The market’s trajectory suggests a diversification of product offerings, moving beyond the current focus on either display-less audio-centric devices or camera-laden AR glasses. The future may hold a spectrum of smart eyewear, each designed to meet specific consumer needs and address evolving societal concerns.
A Brief Chronology of Smart Glasses Evolution
The concept of smart glasses has been evolving for decades, with early iterations often appearing more like science fiction than practical technology. The initial public forays into the market were met with mixed reception and technological limitations.
-
Early Concepts and Prototypes: Visions of augmented reality and heads-up displays have been present in popular culture and research labs since the latter half of the 20th century. Early prototypes often struggled with bulkiness, power consumption, and rudimentary functionality.
-
Google Glass Era (2013-2015): Google Glass represented a significant public push into the consumer smart glasses market. While it offered innovative features like voice commands and a forward-facing camera, it faced substantial criticism regarding privacy, social acceptance, and its high price point, ultimately leading to its discontinuation for consumers.
-
The Rise of Niche and Enterprise Solutions (Mid-2010s): Following the challenges of Google Glass, the smart glasses market saw a shift towards enterprise applications. Companies like Vuzix and RealWear developed ruggedized smart glasses for industrial, medical, and logistics sectors, focusing on hands-free information access and task guidance.
-
Emergence of Display-Less Smart Glasses (Late 2010s – Early 2020s): A new category of smart glasses began to gain traction, prioritizing audio, basic AI assistance, and camera functionality without an integrated display. These devices, often styled as regular eyewear, offered a more discreet and socially acceptable way to access smart features.
-
Meta’s Strategic Entry and the Ray-Ban Partnership (Early 2020s): Meta, under its Reality Labs division, made a significant investment in the smart glasses space. The partnership with Ray-Ban to create Meta smart glasses marked a pivotal moment, bringing a well-known fashion brand into the burgeoning market and focusing on everyday utility and social media integration.
-
AI Integration and Accelerated Growth (2025-2026): The integration of advanced Artificial Intelligence capabilities, powered by increasingly sophisticated AI models, has become a key differentiator. This has fueled the recent explosive growth, with AI-powered features enhancing everything from voice commands and information retrieval to contextual awareness and proactive assistance. The data from Counterpoint Research for the first half of 2026 clearly illustrates this acceleration, positioning smart glasses as a significant and rapidly evolving segment of the wearable technology market.
Broader Implications for the Tech Industry and Society
The sustained growth of the smart glasses market carries significant implications beyond the immediate technological advancements.
1. Evolution of Human-Computer Interaction: Smart glasses represent a shift towards more integrated and intuitive human-computer interfaces. As these devices become more capable and socially accepted, they have the potential to fundamentally alter how we access information, communicate, and interact with the digital world, moving beyond the confines of smartphones and screens.
2. Data Collection and Privacy Landscape: The proliferation of cameras and sensors in wearable devices raises critical questions about data collection, ownership, and privacy. The industry will likely face increased scrutiny from regulators and the public, necessitating robust ethical guidelines and transparent data handling practices. The development of camera-free alternatives is a direct response to these concerns, highlighting a growing awareness of user privacy.
3. Blurring Lines Between Physical and Digital Worlds: Augmented reality glasses, in particular, promise to blend the digital and physical realms in unprecedented ways. This could revolutionize fields such as education, healthcare, retail, and entertainment, offering new avenues for immersive experiences and information delivery.
4. The Future of Personal Technology: Smart glasses could eventually become a primary personal computing device for many, complementing or even supplanting smartphones for certain tasks. The convenience of always-on access to information and AI assistance, seamlessly integrated into daily life, is a compelling proposition for consumers.
As the smart glasses market continues its rapid ascent, it is poised to reshape our technological landscape, presenting both exciting opportunities and significant challenges that will require careful consideration and responsible innovation from manufacturers, policymakers, and consumers alike.